Commercial General Liability Insurance in Ontario: Coverage, Cost and Who Needs It
CGL is the foundation of almost every Ontario business policy. Here is what it covers, what limits to carry, what drives the cost, and who needs it.
Read moreR.I.B. (Ontario) Licensed Broker · Independent · Serving all of Ontario
Commercial
Reviewed by Suneet Sharma, R.I.B. (Ontario) Licensed BrokerLast updated
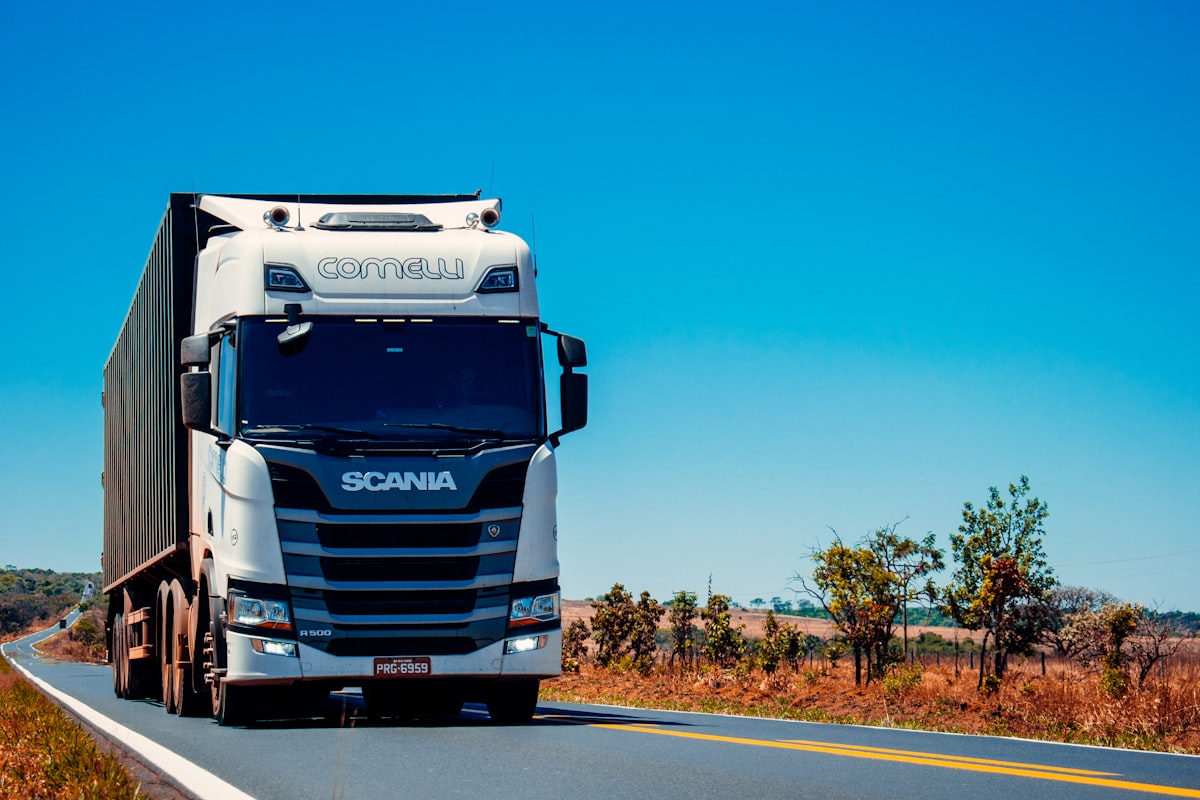
In Ontario, a personal auto policy is generally meant for personal driving and commuting, while you usually need commercial auto insurance if the vehicle is used to earn income — deliveries, carrying tools or goods, driving to client sites, or if the vehicle is owned by a business. Where exactly the line falls depends on the insurer and how the vehicle is used, which is why it's important to describe your driving accurately when you buy or renew.
Driving from home to the same workplace and back is usually treated as commuting, and most personal policies are rated for it. Insurers will ask how far you commute and how often, because it affects the price, but it doesn't make the vehicle commercial.
Business use starts when the driving is part of the work itself: visiting clients, travelling between job sites, carrying samples or products, transporting other people for pay, or making deliveries. Some insurers can add occasional business use to a personal policy; others will want a commercial policy. The answer depends on how often, what you carry, and who owns the vehicle.
Food delivery, parcel delivery and ride-sharing are the areas where I see the most confusion. A standard personal policy usually isn't intended to cover driving for pay. Some insurers offer endorsements designed for delivery or ride-share drivers, and the platforms themselves may carry insurance for certain periods of a trip — but what's covered and when varies, and it doesn't automatically fill every gap.
If you've started driving for an app, tell me before your next shift. It's a short conversation, and it's far better than discovering a gap after an accident.
Contractors, plumbers, electricians, landscapers and other trades often use a pickup or van loaded with tools and materials. Two separate questions come up:
My commercial auto insurance page explains how these pieces fit together, and if you're in York Region, see commercial insurance in Vaughan; in the Golden Horseshoe, see business insurance in Hamilton.
If the ownership is in the name of your corporation, the vehicle generally needs to be insured on a commercial policy in the company's name. This is common for incorporated contractors, consultants and small businesses that lease vehicles through the company. It also matters for liability: when the business owns the vehicle, the business needs to be the insured party.
If the vehicle is personally owned but used heavily for the business, the right structure depends on the specifics. I'll look at ownership, use and drivers together before recommending personal or commercial.
On a personal policy, insurers expect you and listed household members to be the drivers. Once employees drive a business vehicle, the insurer will usually want each regular operator named, and may review their driving records. Letting an unlisted employee drive regularly is a common way to run into problems at claim time.
When a client isn't sure whether their driving counts as personal or business use, I work through a short set of questions. The answers usually make the right policy obvious:
Your premium is based on the information you give the insurer. If a vehicle is used for business but insured as personal-use only, the insurer may treat that as a misrepresentation. Depending on the facts and the policy wording, a claim could be denied or reduced, and the policy could be cancelled. Disclosing accurately costs you a conversation; not disclosing can cost far more.
As a business adds vehicles, insuring each one separately gets harder to manage. Many insurers offer fleet policies once you reach a certain number of vehicles — the threshold varies by insurer, often somewhere around a handful of units. A fleet policy puts every vehicle and driver under one policy with one renewal date. See fleet insurance for how I set these up, and for heavier vehicles, my commercial truck insurance page and commercial truck insurance guide.
If your driving is truly personal, my personal auto insurance page covers how to get the right coverage at a fair price.
About this article: I'm Suneet Sharma, an independent insurance broker licensed in Ontario (R.I.B. (Ontario)), working out of downtown Toronto through Unibrokers. This article is general information about commercial and personal auto insurance in Ontario, reviewed by a licensed broker. It isn't advice for your specific policy — wordings and underwriting rules differ between insurers, so always confirm the details of your own coverage. You can read how I write and review content in my editorial policy.
Using your vehicle for work? Call me at (437) 474-1333 or request a quote, and I'll make sure your policy matches how you actually drive.
Get a free quoteWritten and reviewed by Suneet SharmaR.I.B. (Ontario) Licensed Insurance Broker · Unibrokers
Suneet Sharma is an independent, R.I.B. (Ontario) licensed insurance broker based in downtown Toronto and brokered through Unibrokers. He compares 12+ of Canada’s top-rated insurers to build commercial and personal coverage around each client’s real risks — and stays their single point of contact through renewals and claims.
Specialises in: Business & commercial insurance · Commercial auto & fleet · Home & tenant insurance · Car / auto insurance · Condo insurance · Liability, cyber, E&O & D&O · Travel & Super Visa
Every page on this site is written and reviewed by a licensed Ontario insurance broker, checked against policy wordings and regulator guidance, and updated as coverage rules and the market change. It’s general information, not advice for your specific situation — for that, get a quick quote or call. Read the editorial policy.
Keep reading
CGL is the foundation of almost every Ontario business policy. Here is what it covers, what limits to carry, what drives the cost, and who needs it.
Read moreA practical 2026 look at what commercial insurance actually costs Ontario businesses, what moves the price, and how to build a program that protects you without overpaying.
Read moreFrom commercial general liability to cyber coverage, here are the five insurance policies that form the backbone of protection for an Ontario small business — and how to know which you actually need.
Read moreSend one message and get a free, no-obligation review of your coverage — commercial or personal. If you’re already well covered, I’ll tell you that too.